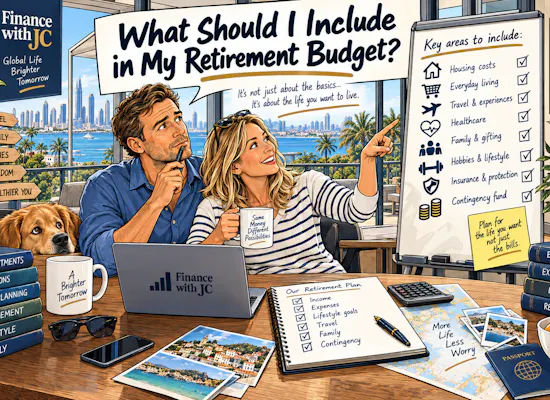
What Should I Include in My Retirement Budget?
A retirement budget should include far more than your normal monthly bills.
Most people remember:
- housing
- food
- utilities
- transport
- insurance
But the bigger planning errors often come from the things that do not happen every month.
Travel.
Healthcare.
Helping children.
Replacing a car.
Property repairs.
Relocation.
Long-term care.
Tax.
Large one-off purchases.
And inflation.
That is why a retirement budget should not simply answer:
“What do I spend each month today?”
It should answer:
“What will my life actually cost once I stop working, including the irregular expenses and changes that are easy to miss?”
For expats, the calculation can be more complicated because retirement may involve more than one country, more than one currency and more than one tax system.
A good starting point is to build the budget alongside your wider retirement planning for expats, because the spending number is what ultimately determines how much capital and income you need.
People also ask
What should be included in a retirement budget?
A retirement budget should normally include essential living costs, housing, healthcare, insurance, travel, hobbies, transport, family support, tax, property costs, large one-off spending and a contingency allowance.
How much will I spend in retirement?
It depends on your lifestyle. Some costs may fall when you stop working, but travel, leisure and healthcare may rise. The most reliable approach is to start with your actual current spending and adjust it for how you expect retirement to look.
Should I include inflation in my retirement budget?
Yes. A retirement lasting 20, 30 or 40 years means today's spending figure will not stay static. Your plan should allow for inflation rather than assuming your costs remain flat forever.
Should healthcare be separate in a retirement budget?
Yes. Healthcare is one of the most commonly underestimated retirement costs, particularly for expats who may need private medical insurance, international cover or out-of-pocket treatment.
How much should I allow for unexpected costs?
There is no universal amount, but your retirement budget should include a contingency for irregular costs such as repairs, family emergencies, medical costs, travel changes and large purchases.
At a glance
- Start with your current real spending, not an arbitrary retirement figure.
- Separate essential spending from lifestyle spending.
- Include irregular annual and one-off costs.
- Budget for healthcare separately.
- Include housing costs even if the mortgage is paid off.
- Allow for travel, hobbies and family support.
- Include tax where relevant.
- Model inflation.
- Include replacement costs for cars, appliances and property.
- Build in a contingency.
- Expats should also model currency, future residence and relocation costs.
- Your spending is likely to change through retirement rather than stay flat.
The short answer
A retirement budget should normally include:
- Housing.
- Utilities.
- Food and household spending.
- Transport.
- Healthcare and insurance.
- Travel.
- Hobbies and leisure.
- Family support.
- Tax.
- Property maintenance.
- Car and appliance replacement.
- Technology and communications.
- Gifts and celebrations.
- Long-term care.
- Relocation costs.
- Large one-off spending.
- Emergency and contingency money.
- Inflation.
The most important thing is not the number of categories.
It is making sure the budget reflects how you genuinely expect to live.
Start with what you spend now
The easiest way to underestimate retirement spending is to guess.
Do not start with:
“I think we could live on £40,000 a year.”
Start with your actual bank and credit-card statements.
Look at the last 12 months.
Ideally, look at two or three years if your spending is irregular.
Group the spending into categories.
Then ask:
- Which costs disappear when I stop working?
- Which stay the same?
- Which rise?
- Which new costs appear?
- Which costs happen only every few years?
This gives you a much better baseline.
A proper retirement income plan should start by clarifying essential spending, lifestyle goals, healthcare, travel, family support and unexpected costs before deciding how much income the assets need to produce.
1. Housing
Housing is often the largest retirement expense.
Include:
- rent or mortgage
- service charges
- ground rent
- property tax
- homeowners association fees
- maintenance
- repairs
- buildings insurance
- contents insurance
- gardening
- cleaning
- security
- air-conditioning maintenance
- pool maintenance
- utilities
Even if your mortgage is fully repaid, housing is not free.
Properties still need maintenance.
Roofs, kitchens, bathrooms, air-conditioning systems, boilers and appliances eventually need replacing.
If you plan to move in retirement, also consider:
- selling costs
- buying costs
- legal fees
- removals
- furnishing
- deposits
- renovation
For expats, housing costs can change dramatically depending on where you retire.
That is one reason how to retire abroad should be modelled around actual housing, healthcare, travel and relocation assumptions rather than only investment returns.
2. Food and household spending
Include:
- groceries
- household items
- cleaning supplies
- eating out
- takeaway
- alcohol
- household help
- subscriptions
Do not assume food spending automatically falls in retirement.
You may cook more.
But you may also eat out more because you have more free time.
The right budget is based on your habits, not a generic percentage.
3. Utilities
Include:
- electricity
- water
- gas
- air-conditioning
- internet
- mobile phones
- TV subscriptions
- streaming services
Some of these can rise after retirement because you spend more time at home.
For someone retiring in the UAE, air-conditioning and utilities can be meaningful.
For someone returning to the UK, heating costs may matter more.
4. Transport
Retirement does not mean transport disappears.
Include:
- car payments
- fuel
- insurance
- servicing
- repairs
- registration
- parking
- taxis
- public transport
- flights
- car replacement
One commonly missed cost is replacing the car.
If you expect to buy a £30,000 car every eight years, that is still a retirement expense even though it does not happen annually.
It can be useful to spread large replacement costs across the plan.
5. Healthcare
Healthcare deserves its own category.
This is particularly important for expats.
You may need:
- private medical insurance
- international health insurance
- dental care
- optical care
- prescriptions
- physiotherapy
- specialist treatment
- screening
- elective treatment
- travel for medical care
- excesses and deductibles
Healthcare costs may also rise later in retirement.
If you are retiring abroad, Finance with JC's retirement-abroad framework specifically includes healthcare alongside spending, tax, currency and estate planning.
Do not assume today's employer-provided medical insurance continues after you stop working.
Find out what the replacement cover would actually cost.
6. Insurance
You may still need:
- health insurance
- home insurance
- car insurance
- travel insurance
- life insurance
- long-term care insurance, where relevant
Some protection needs may reduce in retirement.
Others may increase.
Review each policy rather than cancelling everything automatically when work stops.
7. Travel
Travel is one of the most underestimated retirement expenses.
You may finally have time to do more of it.
Include:
- annual holidays
- long-haul flights
- family visits
- accommodation
- travel insurance
- cruises
- upgraded flights
- second-home travel
- trips back to your home country
For expats, family may be spread around the world.
That can mean regular travel is not really discretionary.
It may be part of normal retirement life.
8. Hobbies and leisure
Retirement is supposed to contain something beyond paying bills.
Include:
- golf
- gym
- clubs
- hobbies
- restaurants
- theatre
- sport
- memberships
- classes
- events
- hobbies requiring equipment
- boats or recreational vehicles, where relevant
Do not build a retirement plan that only funds survival.
The lifestyle spending is often the reason you wanted financial independence in the first place.
9. Family support
This is easy to underestimate.
You may want to help with:
- university
- house deposits
- weddings
- grandchildren
- family emergencies
- elderly parents
- regular gifts
- school fees
- childcare
If supporting family is likely, put it into the plan.
Do not pretend it will never happen and then treat every gift as an unexpected emergency.
10. Tax
Your budget should be based on what you actually need to spend after tax.
Depending on where you live and where income comes from, you may need to allow for:
- pension income tax
- investment income tax
- capital gains tax
- property tax
- rental income tax
- local taxes
- wealth taxes in some jurisdictions
For expats, tax residence can materially alter the amount you need to withdraw from pensions and investments.
That is why retirement spending should be coordinated with the income strategy rather than viewed separately.
11. Property repairs and major maintenance
Do not only include routine maintenance.
Also allow for:
- new kitchen
- bathrooms
- roof repairs
- air-conditioning replacement
- boiler replacement
- painting
- flooring
- structural work
- furniture
- appliances
A retirement budget can look fine for ten years and then be disrupted by a £30,000 property bill.
The plan needs to absorb these events.
12. Technology
Include:
- phones
- laptops
- tablets
- TVs
- home technology
- software subscriptions
- cloud storage
- internet upgrades
Most of these are small individually.
But they recur.
And devices need replacing.
13. Gifts and celebrations
Budget for:
- birthdays
- Christmas
- weddings
- grandchildren
- anniversaries
- family events
These are predictable even if the exact amount is not.
14. Long-term care
This is one of the hardest costs to estimate.
You may never need significant care.
Or it could become one of the largest late-life expenses.
Your plan should at least consider:
- care at home
- assisted living
- nursing care
- support for a spouse
- moving closer to family
You do not necessarily need to pre-fund the worst-case scenario entirely.
But pretending the risk does not exist is not good planning.
15. Relocation
For expats, relocation can be a major retirement expense.
You may decide to:
- stay in the UAE
- return to the UK
- move to Europe
- split time between countries
- move closer to children later
Include:
- flights
- shipping
- deposits
- legal costs
- tax advice
- visas
- residence permits
- health insurance
- temporary accommodation
- furnishing a new home
Finance with JC's retirement planning for British expats in the UAE specifically reflects that the plan needs to account for spending, healthcare, currency and future country moves.
16. One-off spending
Create a separate list for spending that will not happen every year.
For example:
- £25,000 car at age 63
- £15,000 family wedding contribution
- £40,000 property renovation at 68
- £20,000 major holiday
- £50,000 helping a child with a deposit
These costs should appear in your retirement cash-flow plan in the years you expect them.
This is far more realistic than hiding them inside a generic annual spending figure.
17. Emergency and contingency spending
Something unexpected will happen.
You just do not know what it is yet.
Build in a margin.
That may cover:
- medical emergencies
- family support
- urgent property work
- legal costs
- unexpected travel
- higher insurance costs
- temporary currency shocks
A retirement plan that only works when nothing unexpected happens is not a strong plan.
18. Inflation
This is essential.
If your retirement budget is £50,000 today, it should not remain £50,000 in every future year.
The same lifestyle will usually cost more over time.
You do not need to know exactly what inflation will be.
You do need to model it.
Even modest inflation compounds over 20 or 30 years.
Separate essential spending from lifestyle spending
One of the most useful things you can do is divide spending into:
Essential
Costs you need to pay regardless of markets.
For example:
- housing
- food
- healthcare
- utilities
- insurance
Discretionary
Costs you could reduce temporarily.
For example:
- travel
- restaurants
- gifts
- hobbies
- upgraded flights
This matters because flexible spending can protect a retirement portfolio after poor investment returns.
If markets fall sharply, cutting discretionary spending for a year or two may reduce the need to sell investments at depressed prices.
Do not assume retirement spending stays flat
Retirement often moves through phases.
Go-Go years
Early retirement may involve:
- more travel
- hobbies
- restaurants
- family visits
- active leisure
Spending can be relatively high.
Slow-Go years
Travel and activity may reduce.
Some discretionary spending may fall.
No-Go years
Leisure costs may reduce further, while:
- healthcare
- home support
- care
may increase.
Your retirement budget should reflect that.
Not every category needs to rise forever.
A worked example
Imagine a couple approaching retirement with the following expected annual spending:
Essentials
- Housing and property: £12,000
- Food and household: £8,000
- Utilities and communications: £4,000
- Transport: £5,000
- Healthcare and insurance: £6,000
Essential total: £35,000
Lifestyle
- Travel: £12,000
- Restaurants and leisure: £6,000
- Hobbies and memberships: £4,000
- Gifts and family: £3,000
Lifestyle total: £25,000
Annual budget
£60,000
But they also expect:
- £30,000 car replacement every eight years
- £20,000 home refurbishment in five years
- £25,000 contribution to a daughter's wedding
- possible future healthcare costs
Their retirement plan should not simply model £60,000 a year.
It should model £60,000 plus those one-off costs in the relevant years.
That can materially change how much they need.
Expat example: retiring from Dubai
Imagine a British couple currently living in Dubai.
They intend to retire at 60 but are unsure whether they will stay in the UAE or return to the UK.
Their current budget includes:
- UAE rent
- private medical insurance
- flights to the UK
- two cars
- frequent travel
- household help
If they return to the UK:
- rent may disappear if they own a home
- private healthcare may fall
- household help may reduce
- flights may reduce
- council tax and home maintenance may rise
- heating costs appear
- travel patterns change
There is no single retirement budget.
They need at least two versions.
This is exactly why retirement planning for expats needs to remain flexible around future residence.
What about Americans abroad?
The same budgeting principles apply, but the income planning can be different.
American retirees overseas may need to coordinate:
- 401(k)s
- IRAs
- Roth IRAs
- Social Security
- healthcare
- US tax
- local tax
- currency
- foreign property
Finance with JC's retirement planning for Americans abroad framework specifically highlights healthcare, tax residence, currency and retirement account withdrawals as core considerations.
Self-diagnostic: is your retirement budget complete?
Score one point for each “yes”.
- I know my current annual spending.
- I have separated essential and discretionary spending.
- I have included housing maintenance.
- I have included healthcare.
- I have included travel.
- I have included car replacement.
- I have included family support.
- I have included tax.
- I have included large one-off costs.
- I have included a contingency.
- I have modelled inflation.
- I have considered how spending changes later in retirement.
Green: 9 to 12
Your retirement budget is likely detailed enough to start building a meaningful cash-flow plan.
Amber: 5 to 8
You have a good starting point, but important costs may still be missing.
Red: 0 to 4
Your retirement figure is probably too rough to rely on.
Common mistakes
Using current monthly bills only
Problem
Retirement planning is based on ordinary monthly expenditure.
Why it matters
Large irregular costs disappear from the calculation.
What to do
Review at least a full year of spending and add one-off costs separately.
Assuming the mortgage disappearing solves everything
Problem
Housing costs are assumed to become zero.
Why it matters
Maintenance, service charges, insurance and repairs remain.
What to do
Budget for the property even if it is debt-free.
Forgetting healthcare
Problem
Employer medical cover is assumed to continue.
Why it matters
Retirement may require private or international health insurance.
What to do
Get realistic healthcare cost estimates before retirement.
Underestimating travel
Problem
Retirement travel is treated as an occasional luxury.
Why it matters
For many expats, visiting family across countries is a permanent part of life.
What to do
Build travel into the normal budget.
Ignoring inflation
Problem
Today's spending figure is used forever.
Why it matters
Purchasing power declines over time.
What to do
Increase future spending assumptions.
Forgetting the expensive years
Problem
Cars, renovations and family gifts are ignored.
Why it matters
These can create large portfolio withdrawals.
What to do
Model them individually.
Making every expense essential
Problem
The plan assumes spending can never change.
Why it matters
Flexibility is valuable during poor investment markets.
What to do
Separate essential and discretionary spending.
What to review before finalising your retirement budget
Housing
Where will you live, and will you own, rent or move?
Healthcare
What does medical insurance cost after work stops?
Travel
How often will you travel and visit family?
Family
Will you help children, grandchildren or parents?
Tax
How much gross income is needed to fund your net spending?
Currency
What currency will the spending actually be in?
Property
What repairs and major costs are likely over 20 or 30 years?
Inflation
How does spending rise over time?
Long-term care
What happens if one spouse needs support later?
Contingency
How much margin does the plan have?
What happens next
Step 1: pull 12 months of transactions
Use bank accounts and credit cards.
Step 2: categorise everything
Separate essential, lifestyle and one-off spending.
Step 3: remove work-specific costs
This might include commuting, work clothing or professional costs.
Step 4: add retirement-specific costs
Include healthcare, travel, hobbies and relocation.
Step 5: add major future expenditure
Put cars, renovations and family gifts onto the timeline.
Step 6: adjust for inflation
Do not hold the budget flat indefinitely.
Step 7: build more than one scenario
Especially if you are an expat and have not yet decided where you will retire.
Step 8: compare the spending against your assets
Then ask whether pensions, investments, cash and other income can realistically support it.
You may also like
Conclusion
A good retirement budget should tell you what retirement actually costs.
Not just the monthly bills.
Not just the essentials.
And not just today's spending.
It should include:
- normal living costs
- lifestyle
- travel
- healthcare
- tax
- family support
- property
- car replacement
- major one-off spending
- contingency
- inflation
- possible long-term care
For expats, it should also reflect where you might live, what currency you will spend and what costs may change if you move again.
The key question is not:
What are my bills today?
It is:
What will the life I actually want in retirement cost, including the years when things do not go perfectly?
If you are approaching retirement and want to work out what your lifestyle is likely to cost and whether your pensions and investments can support it, book an introductory call with Josh Clancey.
FAQ
What are the main expenses to include in retirement?
Housing, food, utilities, transport, healthcare, insurance, travel, hobbies, family support, tax, major purchases and unexpected costs.
How should I estimate retirement spending?
Start with 12 months of actual spending, remove costs that disappear after work, add retirement-specific costs and include irregular large expenses separately.
Will I spend less in retirement?
Possibly, but not necessarily. Work costs may fall while travel, hobbies and healthcare may rise. Spending often changes over different phases of retirement.
How much should I budget for healthcare?
It depends heavily on where you live and whether you have access to public healthcare. Expats should obtain realistic private or international medical insurance estimates.
Should I include mortgage payments?
Yes, if the mortgage will continue after retirement. Even if it is repaid, include ongoing property maintenance, insurance and other ownership costs.
Should I budget for helping my children?
If you genuinely expect to help with education, house deposits, weddings or other costs, include it rather than treating it as an unexpected expense later.
How do I account for inflation?
Model your spending increasing over time rather than assuming today's figure remains unchanged.
What one-off costs do retirees forget?
Cars, property refurbishment, family weddings, large holidays, relocation, major healthcare and helping children are common examples.
Is a retirement budget different for expats?
Yes. Expats may need to consider private healthcare, international travel, currency, tax residence, visas, relocation and more than one possible retirement country.