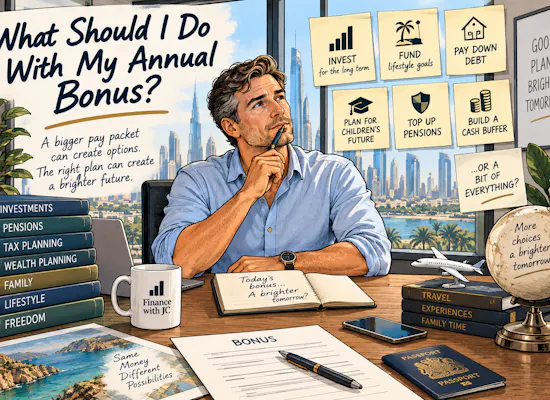
What Should I Do With My Annual Bonus?
An annual bonus can be one of the most valuable financial opportunities you get each year.
It can also disappear remarkably quickly.
A holiday.
A new car.
A few upgrades.
Some money left in cash.
Then, six months later, you cannot quite remember where it went.
There is nothing wrong with enjoying part of a bonus.
You worked for it.
But a large bonus can do something your monthly salary often cannot.
It can make a meaningful jump forward.
It can:
- clear expensive debt
- build a proper emergency reserve
- fund a house deposit
- increase retirement savings
- build an investment portfolio
- pay down a mortgage
- fund education costs
- improve family protection
- create financial independence
- give you more flexibility if you change jobs or countries
For expats, this matters even more.
A strong salary can make everyday finances comfortable, but large annual bonuses are often where real wealth accumulation happens.
If you live in Dubai or elsewhere in the UAE, the country does not currently levy personal income tax on individuals. That can make a bonus particularly powerful, although your citizenship, tax residence and future plans may still create tax considerations elsewhere.
The question is not:
What should I buy with my bonus?
The better question is:
What is the highest-value job this money can do for me?
That is a financial-planning question.
If you are building wealth while working abroad, the decision should fit within your wider investment planning as an expat, not be made in isolation.
People also ask
What is the best thing to do with an annual bonus?
There is no single best use. Start by reviewing high-interest debt, emergency cash, short-term goals, retirement planning, investments and any major upcoming expenditure. The best use is the one that strengthens your overall financial position.
Should I invest my whole bonus?
Not necessarily. Investing may be appropriate for money you do not need for several years, but you may first need to repay expensive debt, build cash reserves or fund near-term goals.
How much of my bonus should I save?
There is no universal percentage. The right amount depends on your financial position. Someone with no debt and a strong cash reserve may invest most of it. Someone with high-interest debt or no emergency fund may use the bonus very differently.
Should I use my bonus to pay off my mortgage?
Possibly. Compare the mortgage rate, early repayment charges, liquidity needs, investment opportunities, tax position and how much financial security you value.
Should I spend some of my bonus?
Yes, if you want to. A financial plan does not need to remove enjoyment. The key is deciding the amount deliberately rather than allowing lifestyle spending to absorb the entire bonus.
At a glance
- Do not decide what to do with your bonus on the day it arrives.
- Start by understanding the net amount available after any tax or withholding.
- Clear expensive debt before taking unnecessary investment risk.
- Build or replenish emergency cash.
- Ring-fence money needed in the next few years.
- Invest long-term money according to your goals, time horizon and risk.
- Review pension or retirement contribution opportunities where relevant.
- Consider mortgage repayment, but compare it with keeping liquidity and investing.
- Give yourself permission to enjoy part of the bonus.
- For expats, consider tax residence, currencies and what happens if you move country.
- The aim is to convert a temporary income spike into lasting financial progress.
The short answer
A sensible order for an annual bonus is usually:
- Work out what you actually received after tax or withholding.
- Set aside money for known short-term expenses.
- Repay high-interest debt.
- Build an appropriate emergency fund.
- Review retirement and pension opportunities.
- Invest money you will not need for the long term.
- Consider mortgage or other debt reduction.
- Fund important family or education goals.
- Keep some money for enjoyment.
- Make sure the decision still works if you move country.
Not everyone needs to follow that exact order.
But it gives the bonus a structure.
The main mistake is treating the entire payment as disposable income.
Step 1: do not spend it immediately
This sounds basic.
But it matters.
A bonus feels psychologically different from salary.
Salary pays for life.
A bonus feels like extra money.
That can make it easier to spend.
A useful approach is to move the bonus into a separate account for a few weeks.
Do nothing.
Then make decisions.
This creates distance between receiving the money and spending it.
For a large bonus, that pause can be worth thousands.
Step 2: work out the real amount available
The headline bonus is not always what you actually have to allocate.
Depending on where you live and your tax status, there may be:
- income tax
- payroll withholding
- social security
- pension deductions
- deferred compensation
- employer share-plan deductions
- currency conversion
- other deductions
For US employees, the IRS treats bonuses as supplemental wages for withholding purposes.
For UAE residents, the UAE currently does not impose personal income tax on individuals.
But that does not mean every UAE resident can ignore tax.
For example, an American living in the UAE may still have US tax and reporting obligations. Finance with JC’s financial planning for Americans in the UAE page explains why UAE residence does not automatically remove the US from the picture.
So start with the net amount that is genuinely available.
Step 3: clear expensive debt
If you have expensive unsecured debt, this may be the best use of the bonus.
That can include:
- credit cards
- personal loans
- revolving credit
- expensive car finance
- overdrafts
Suppose you have:
- £20,000 equivalent of debt
- interest cost of 15%
- £50,000 annual bonus
Repaying the debt effectively removes a guaranteed 15% financing cost.
Finding an investment that reliably produces the same return after fees, tax and risk is a very different proposition.
This does not mean every debt should be repaid.
A low-rate mortgage may need different analysis.
But high-cost consumer debt usually deserves priority.
Step 4: build the emergency fund
A bonus can be an ideal way to build the cash reserve you have been meaning to create.
The appropriate amount depends on:
- job security
- family situation
- monthly expenses
- insurance
- visa status
- whether one or two people earn
- how easy it would be to find new work
- where you would go if employment ended
For expats, job loss can be more disruptive than it is for someone living permanently in their home country.
Employment can be connected to:
- residency
- housing
- school fees
- health insurance
- relocation
- flights
- visa costs
That means cash reserves matter.
You do not want a market fall to force you to sell long-term investments because you unexpectedly need to fund six months of living expenses.
Step 5: fund known short-term goals
Do not invest money you know you will need soon.
Your bonus may already have jobs waiting for it.
For example:
- school fees
- house deposit
- property renovation
- wedding
- relocation
- car replacement
- university costs
- tax bill
- family support
- planned sabbatical
Money required in the short term may belong in cash or other lower-risk assets rather than equities.
The investment decision should follow the time horizon.
Not the other way around.
Step 6: use the bonus to accelerate investing
Once debt, cash reserves and short-term goals are covered, the bonus may become powerful investment capital.
For example, imagine you receive a £50,000 equivalent bonus every year.
If you invested £35,000 of it each year for ten years, that would mean £350,000 of contributions before any investment growth.
That is how annual bonuses can transform long-term wealth.
The important point is not to chase the investment that performed best last year.
Instead, ask:
- What is the money for?
- When will I need it?
- Which currency will I eventually spend?
- How much investment risk can I tolerate?
- What other assets do I already own?
- Will I remain in this country?
- Could my tax residence change?
- What investment structure remains workable if I move?
This is why investment planning in Dubai should be built around your wider life rather than a product.
Step 7: review pension and retirement opportunities
A bonus can also be used to accelerate retirement planning.
But this is where nationality and residence become important.
If you are UK resident
Pension contributions may offer tax advantages, subject to eligibility and allowances.
For 2026/27, the standard UK pension annual allowance is £60,000, although it may be lower for higher earners or people who have flexibly accessed money purchase pensions. Unused allowance from the previous three tax years may sometimes be carried forward.
If you are a UK expat
Do not assume you can simply pay your bonus into a UK pension and receive the same tax relief you did before leaving.
Eligibility for UK pension tax relief depends on your circumstances.
The broader retirement question may instead be whether the bonus should build accessible investments alongside existing UK pensions.
If you are American abroad
The analysis is different again.
401(k), IRA, Roth IRA, US tax and foreign investment rules may all affect what is sensible.
For Americans in the UAE, the bonus should be considered alongside retirement planning for Americans in the UAE, not simply invested through whatever product is most convenient locally.
The important point is that a bonus can materially accelerate retirement.
But the wrapper matters.
Step 8: should you pay down the mortgage?
This is often a close call.
Using a bonus to reduce a mortgage provides a guaranteed reduction in future interest costs.
It may also:
- reduce monthly expenditure
- improve financial security
- reduce refinancing risk
- move you closer to being debt-free
- make retirement easier
But there is an opportunity cost.
Money used to repay the mortgage is no longer readily available for:
- investing
- emergencies
- business opportunities
- relocation
- education
- future property purchases
Ask:
Would I rather have £50,000 less mortgage debt or £50,000 of additional liquid capital?
The answer depends on:
- mortgage rate
- remaining term
- early repayment penalties
- investment time horizon
- risk tolerance
- retirement plans
- cash reserves
- how much debt worries you
It is not always an investment-return calculation.
Security has value too.
Step 9: invest versus hold cash
Another common outcome is that the bonus simply stays in a bank account.
For a few months, that may be fine.
For ten years, probably not if the money is intended for long-term growth.
Cash is useful for:
- emergencies
- short-term spending
- known liabilities
- optionality
But large permanent cash balances can lose purchasing power to inflation.
The right amount of cash depends on what the money needs to do.
If you already have enough cash, more cash may not improve your position.
That is when the bonus may be better directed toward longer-term goals.
Step 10: do not forget currency
This is particularly important for expats.
You may receive your bonus in:
- AED
- USD
- GBP
- EUR
- SAR
- another currency
But your future goals may be in a different currency.
For example:
- salary and bonus in AED
- UK property in GBP
- investments in USD
- retirement planned in EUR
Do not automatically convert everything into sterling because you are British.
And do not automatically leave everything in dollars because the dirham is pegged to the dollar.
Think about what the money is ultimately for.
Your assets should gradually align with your future liabilities and spending.
Step 11: think about returning home
One of the most important questions for expats is:
Where might I live next?
A bonus investment that works well while you are in the UAE may need to be reconsidered before moving to another country.
If you expect to return to Britain, investment structure, gains, income, pensions and tax residence may all become relevant.
Finance with JC’s moving back to the UK financial planning page covers the wider issues that should be reviewed before UK residence resumes.
This is why portability matters.
Your investment strategy should survive a change of country.
Step 12: spend some of it
This matters too.
You do not have to optimise every penny.
A bonus can be enjoyed.
The problem is not spending £5,000 of a £50,000 bonus on a good holiday.
The problem is spending £50,000 because there was never a plan.
One approach is to decide in advance:
- an amount for long-term wealth
- an amount for short-term goals
- an amount for enjoyment
The exact percentages should depend on your circumstances.
For example, someone already financially secure may quite reasonably spend more.
Someone with no investments, no emergency reserve and large debts should probably behave differently.
Good financial planning should improve your life now and later.
A worked example: £100,000 bonus in Dubai
Imagine you receive a £100,000 equivalent annual bonus while living in Dubai.
You have:
- no credit-card debt
- a £400,000 mortgage
- £25,000 cash reserve
- £300,000 already invested
- UK pensions
- two children
- plans to retire in Europe
- no immediate intention to leave Dubai
One possible planning process could be:
£15,000: increase the emergency reserve
This creates more flexibility around employment, family costs and relocation.
£10,000: planned family spending
A holiday, school costs and other known expenses.
£15,000: mortgage repayment
This reduces leverage and future interest.
£60,000: long-term investment
This is allocated into a diversified portfolio aligned with retirement, currency and future residence.
That is only an example.
The correct split may be completely different.
The point is that every part of the bonus has a job before the money is spent.
Another example: bonus but expensive debt
Imagine someone receives £50,000 but also has:
- £15,000 credit-card debt
- £10,000 personal loan
- £5,000 cash
- no investments
Immediately investing the entire £50,000 may not be sensible.
A stronger approach might involve:
- clearing the expensive debt
- increasing emergency cash
- investing the remaining amount
- beginning a monthly investment plan from future salary
The goal is not to maximise the amount invested today.
It is to strengthen the whole balance sheet.
Another example: bonus close to retirement
Imagine you are 58.
You receive a £75,000 bonus.
You already have substantial investments and pensions but plan to retire at 60.
Your priority may be different.
Rather than taking more equity risk, the bonus might help:
- build two years of retirement cash
- pay off the remaining mortgage
- fund planned travel
- cover relocation costs
- reduce the amount that needs to be withdrawn from investments during the first years of retirement
For someone close to retirement, the bonus may be more valuable as a risk-management tool than as additional investment risk.
This should be considered as part of retirement planning for expats.
Another example: American in the UAE
An American executive in Dubai receives a $150,000 bonus.
They already have:
- a US 401(k)
- a Traditional IRA
- US brokerage accounts
- UAE cash
- children
- a non-US spouse
They should not simply put the bonus into a local investment without considering US rules.
US citizens remain within the US tax system, and foreign investments can create additional tax and reporting considerations.
The bonus should be reviewed as part of the entire US/UAE financial plan.
A simple bonus hierarchy
When a bonus arrives, ask these questions in order.
1. Is there any expensive debt?
If yes, review that first.
2. Do I have enough emergency cash?
If no, strengthen the reserve.
3. Is any of this money needed in the next few years?
If yes, ring-fence it.
4. Am I behind on retirement?
If yes, look at pension and long-term investing opportunities.
5. Is my mortgage a problem?
If yes, compare repayment against investing.
6. Am I already overexposed to cash, property or one market?
If yes, use the bonus to improve diversification.
7. Will I move country?
If yes, make sure the strategy remains portable.
8. What do I actually want to enjoy?
Choose the amount deliberately.
Self-diagnostic: is your bonus being used well?
Score one point for each “yes”.
- I know the exact net bonus I will receive.
- I have no expensive consumer debt.
- I have an appropriate emergency reserve.
- I have funded known expenses for the next one to three years.
- I know what my long-term investment goals are.
- I know whether I am on track for retirement.
- I know whether paying down debt would improve my position.
- I know which currency my future goals are in.
- I understand the tax implications of where I live.
- I know what happens to my investments if I move country.
- I have decided how much of the bonus I can enjoy.
- I have allocated the money before spending it.
Green: 9 to 12 points
Your bonus is likely being treated as part of a financial plan rather than simply extra spending money.
Amber: 5 to 8 points
You have some structure, but the bonus could probably be allocated more deliberately.
Red: 0 to 4 points
Do not rush to invest or spend it. Review the wider financial picture first.
Common mistakes
Spending first and planning afterwards
Problem
The bonus hits the account and lifestyle spending starts immediately.
Why it matters
The money can disappear before any long-term decision is made.
What to check
Allocate the bonus before spending it.
Investing while carrying expensive debt
Problem
The person wants to invest but has credit cards or costly loans.
Why it matters
The interest cost may exceed the return reasonably expected from investments.
What to check
Compare debt cost against the value of keeping or investing the cash.
Investing money needed soon
Problem
The entire bonus goes into markets even though part is needed next year.
Why it matters
Markets may be down when the money is required.
What to check
Match the investment time horizon to the goal.
Leaving everything in cash
Problem
The bonus accumulates in a current account year after year.
Why it matters
Long-term money may lose purchasing power and miss opportunities for growth.
What to check
Separate emergency and short-term cash from long-term wealth.
Buying a product before making a plan
Problem
The first question becomes “Where should I invest this?”
Why it matters
The right investment depends on what the money is for.
What to check
Define the objective first.
Ignoring future residence
Problem
An expat chooses an investment only because it works in the current country.
Why it matters
Tax, access and reporting may change after relocation.
What to check
Ask whether the structure still works if you move.
Spending none of it
Problem
Every penny is saved because spending feels financially irresponsible.
Why it matters
Money is also there to support the life you want.
What to check
Decide what amount can be enjoyed without undermining longer-term goals.
What to review before allocating your bonus
Cash flow
Make sure regular salary comfortably covers normal spending.
Debt
List mortgage, loans, credit cards and other borrowing with their interest rates.
Emergency reserve
Decide how much accessible cash your family realistically needs.
Short-term goals
List known spending over the next one to three years.
Investments
Review your existing portfolio before adding more money.
Retirement
Check whether you are on track and whether the bonus could materially improve your future position.
Tax
Understand whether the bonus itself is taxed and whether the investment strategy creates tax issues.
Currency
Consider the currency of your future spending rather than just the currency in which the bonus is paid.
Future residence
Think about where you may live in five or ten years.
Family
Include education, property, family support and estate planning where relevant.
What happens next
Step 1: park the bonus
Put it somewhere safe while you make the decision.
Step 2: update your balance sheet
List cash, investments, pensions, property and debt.
Step 3: identify weaknesses
Look for expensive debt, insufficient cash or underfunded goals.
Step 4: prioritise the money
Give each part of the bonus a specific job.
Step 5: invest long-term capital
Only invest the amount that genuinely has a long time horizon.
Step 6: automate the lesson
If the bonus reveals that you could be saving more generally, increase monthly investments too.
Step 7: enjoy part deliberately
Do something worthwhile with the money without undermining the bigger plan.
You may also like
Conclusion
An annual bonus can disappear into lifestyle spending.
Or it can materially change your financial position.
The difference is usually whether the money gets allocated before it gets spent.
You may use some of it to:
- clear debt
- strengthen cash reserves
- invest
- prepare for retirement
- reduce your mortgage
- fund family goals
- prepare for a future move
- enjoy life
There is no universal percentage that should go into each category.
The right allocation depends on where you are starting from.
The key question is not:
What should I spend my bonus on?
It is:
What could this money do today that makes my future materially better?
If you receive significant bonuses and are not sure how to balance investing, debt, pensions, cash and future plans, book an introductory call with Josh Clancey.
FAQ
What should I do first with my annual bonus?
Before spending it, check your net bonus, expensive debt, emergency fund and known short-term expenses. Then decide what can be directed toward longer-term goals.
Should I invest my whole annual bonus?
Not necessarily. Only invest money that has an appropriate time horizon and is not needed for debt repayment, emergencies or near-term spending.
Should I use my bonus to pay off debt?
High-interest debt is often worth prioritising. Mortgage debt requires a more balanced comparison between interest cost, liquidity, investment opportunity and personal security.
How much of my bonus should I save?
There is no fixed percentage that works for everyone. Your financial position, goals, debt, emergency reserves and investment progress should determine the amount.
Should I put my bonus into my pension?
Possibly, depending on your residence, eligibility, tax position and pension allowances. UK residents need to consider the annual allowance and tax-relief rules. Expats may face different eligibility.
What should I do with a bonus in Dubai?
Start by reviewing debt, cash reserves, short-term goals, investments, retirement plans, currencies and future residence. The UAE currently does not impose personal income tax on individuals, but other countries may still have taxing rights depending on your circumstances.
Is it better to invest a bonus or pay down my mortgage?
It depends on the mortgage rate, investment horizon, risk tolerance, liquidity, retirement plans and how much you value being debt-free.
Should I keep my bonus in cash?
Cash can be appropriate for emergencies and short-term goals. Long-term money may be better invested if you can accept investment risk and do not need the capital soon.
Is it OK to spend part of my bonus?
Yes. A sensible financial plan can include enjoyment. Decide the amount consciously before the bonus is absorbed into normal spending.