What Happens to My Retirement Plan If Markets Fall Just After I Retire?
A market fall just after retirement can be much more damaging than the same market fall while you are still working.
Why?
Because you are no longer just investing.
You are withdrawing money as well.
That combination creates one of the most important risks in retirement planning:
sequence-of-returns risk.
If markets fall sharply during the first few years of retirement and you continue withdrawing money from the portfolio, you may be forced to sell investments at depressed prices.
Those assets are then no longer there to participate fully when markets recover.
That can permanently weaken the retirement plan.
Morningstar's retirement research describes sequence-of-returns risk as the danger that losses early in retirement reduce the ability of savings to sustain spending throughout retirement, with the first several years particularly important.
The question is not:
Will markets fall after I retire?
At some point, they almost certainly will.
The better question is:
Can my retirement plan survive a significant fall without forcing me to make bad decisions?
That is where retirement planning for expats becomes much more than simply choosing investments. A good plan needs to show how spending, cash, pensions, investments and future income work together when markets do not behave nicely.
People also ask
What is sequence-of-returns risk?
Sequence-of-returns risk is the danger that poor investment returns early in retirement, combined with withdrawals, reduce the portfolio so much that it becomes harder to recover later.
Is a market crash worse after retirement?
Potentially, yes. While you are working, you may be able to continue contributing to investments during a downturn. In retirement, you may instead be withdrawing from the portfolio, which can magnify the damage.
Should I move everything into cash before retiring?
Usually not. Holding too much cash can reduce long-term growth and increase inflation risk. The goal is normally to balance short-term security with enough growth for a long retirement.
How much cash should I keep in retirement?
There is no single correct amount. The right reserve depends on spending, guaranteed income, investment risk, flexibility and how long you want to avoid selling growth assets after a market fall.
Should I reduce withdrawals when markets fall?
Sometimes, yes. Flexible spending can materially improve resilience. Reducing discretionary withdrawals during poor markets can help preserve the portfolio.
At a glance
- A market fall just after retirement can be more damaging than one later.
- The main risk is being forced to sell investments while prices are depressed.
- The order of investment returns matters, not just the average return.
- The first five to ten years around retirement are especially important.
- Cash reserves can reduce the need to sell growth assets during downturns.
- Guaranteed income can also reduce pressure on the portfolio.
- Flexible spending improves resilience.
- Moving entirely to cash can create inflation and longevity risk.
- Diversification still matters in retirement.
- A good retirement plan should be stress tested before you stop working.
The short answer
If markets fall just after you retire, your plan may still be completely manageable.
But it depends on how the plan was built.
A resilient retirement plan usually has several layers:
- Enough cash or low-volatility assets for near-term spending.
- A diversified investment portfolio.
- Sensible withdrawal levels.
- Some flexibility around discretionary spending.
- Guaranteed income where appropriate.
- A plan for when State Pension or other income begins.
- A process for rebalancing rather than panic selling.
- Regular reviews.
The biggest problem is not the market fall itself.
It is the combination of:
- falling markets
- large withdrawals
- inflexible spending
- poor diversification
- panic selling
That is what can turn a temporary market decline into a permanent retirement problem.
What is sequence-of-returns risk?
Imagine two retirees.
Both start retirement with £1 million.
Both withdraw £40,000 a year.
Both achieve the same average return over 20 years.
But one gets strong investment returns in the first five years.
The other experiences a major market decline immediately after retiring.
The second retiree may finish with considerably less money.
Why?
Because early withdrawals are being taken from a smaller portfolio.
When investments are sold after a market fall, those units are gone.
When markets recover, fewer assets remain to benefit.
This is why the sequence of returns matters.
The average return can be identical.
The outcome can still be very different.
A simple example
Imagine you retire with:
- £1,000,000 portfolio
- £50,000 annual spending requirement
- no guaranteed income initially
Now suppose markets fall 20% shortly after retirement.
Your portfolio falls to around:
£800,000
before withdrawals.
If you then withdraw £50,000, you are taking more than 6% of the reduced portfolio.
If another weak year follows, the problem compounds.
By contrast, if you had £100,000 or £150,000 of cash or short-term assets available for spending, you might be able to avoid selling part of the growth portfolio immediately.
That does not make the market fall disappear.
But it can reduce the damage.
Why retirement changes investment risk
Before retirement, volatility can be uncomfortable.
But you may have:
- salary
- bonuses
- new contributions
- many years before withdrawals
That means falling markets can even create opportunities to buy investments at lower prices.
After retirement, the dynamic changes.
You may no longer be contributing.
You may be taking money out every month.
The portfolio has become an income-producing asset.
That means the same level of volatility can have a very different effect.
This is why a portfolio designed for accumulation should often be reviewed before retirement.
Finance with JC's retirement income planning for expats framework specifically looks at how pensions, investments and cash provide sustainable income after work stops.
The retirement red zone
The period immediately before and after retirement is often described as a critical risk period.
Recent retirement-planning commentary highlights the five years before and after retirement as especially important because this is when sequence risk can have the greatest effect on a portfolio.
That does not mean markets become safe after ten years.
It means the early years deserve special attention because:
- the portfolio is usually largest
- withdrawals have just started
- guaranteed income may not yet have begun
- there is less employment income to fall back on
- a large early loss can affect decades of future withdrawals
That is why the transition into retirement should be planned deliberately.
Strategy 1: hold an appropriate cash reserve
Cash is one of the simplest tools for managing sequence risk.
The purpose is not to maximise return.
It is to give you somewhere to draw spending from when markets are weak.
For example, you might hold:
- one year of essential spending
- two years of expected withdrawals
- a broader short-term reserve
The right amount depends on the plan.
Too little cash may force you to sell investments during a downturn.
Too much cash may create inflation drag and reduce long-term growth.
The right balance is personal.
Strategy 2: separate short-term and long-term money
A useful retirement structure is to think in time horizons.
Short-term bucket
Money needed over the next few years.
This might include:
- cash
- money market funds
- short-duration bonds
- other lower-volatility assets
Medium-term bucket
Money needed later.
This might include:
- diversified bonds
- lower-volatility investments
- balanced assets
Long-term bucket
Money needed much later.
This may remain invested for growth.
That can include:
- global equities
- growth assets
- diversified long-term investments
This does not guarantee success.
But it can reduce the pressure to sell long-term assets after a short-term market fall.
Strategy 3: make spending flexible
This is one of the strongest tools available.
Not all retirement spending is essential.
You may have:
Essential spending
- housing
- food
- healthcare
- utilities
- insurance
Discretionary spending
- travel
- restaurants
- hobbies
- large gifts
- upgraded flights
- expensive purchases
If markets fall sharply, temporarily reducing discretionary spending may materially improve the plan.
For example, a retiree normally spending £60,000 might reduce spending to £50,000 for two years after a major downturn.
That £20,000 reduction across two years leaves more capital invested during the recovery.
This is why retirement budgeting should separate essential and discretionary expenditure rather than treating every pound as fixed.
Strategy 4: use guaranteed income carefully
Guaranteed income can reduce pressure on investment portfolios.
This may include:
- State Pension
- defined benefit pensions
- annuity income
- Social Security
- other state pensions
Suppose you need £50,000 a year.
If £25,000 eventually comes from guaranteed sources, the investment portfolio only needs to provide the remaining £25,000.
That reduces withdrawal pressure.
It can also make market volatility psychologically easier to tolerate.
This is one reason retirement planning for British expats in the UAE should look at all future pension income, not just the size of the investment portfolio.
Strategy 5: avoid panic selling
The worst moment to redesign your investment strategy is often in the middle of a market crash.
If the plan was sensible before markets fell, selling growth assets after a major decline can lock in losses.
Instead, the plan should define in advance:
- where withdrawals come from
- what gets rebalanced
- which spending can be reduced
- when cash reserves are used
- when assets are replenished
That gives you a process.
A process is much easier to follow than trying to make emotional decisions during a crisis.
Strategy 6: rebalance rather than react
Market falls change the portfolio mix.
Suppose your target is:
- 60% equities
- 40% bonds and cash
After a major equity fall, you may end up closer to:
- 50% equities
- 50% bonds and cash
Rebalancing may involve using some of the relatively stronger assets to restore the intended allocation.
That is different from abandoning equities because they have fallen.
The decision should be based on the investment plan.
Not recent headlines.
Strategy 7: avoid withdrawing more than you need
This becomes particularly important early in retirement.
Large withdrawals for:
- cars
- property
- gifts
- travel
- helping children
can be much more damaging if they happen during a market decline.
That does not mean you cannot spend.
It means timing matters.
If markets are already down heavily, delaying a discretionary £50,000 purchase may materially improve the portfolio's chance to recover.
A good retirement budget should therefore identify major one-off expenses before retirement starts.
Strategy 8: do not become too conservative
This is the other side of the problem.
After seeing markets fall, retirees sometimes want to move everything into cash.
That may feel safe.
But retirement may last 30 years or more.
Cash creates other risks:
- inflation
- reduced growth
- longevity risk
- loss of purchasing power
A retirement portfolio normally still needs some growth assets because the money may need to support spending for decades.
The goal is not to eliminate investment risk.
It is to manage it.
A worked example
Imagine Sarah retires at 60 with:
- £1 million invested
- £100,000 cash
- £50,000 annual spending
- State Pension starting at 67
- no mortgage
Shortly after retirement, markets fall 25%.
Plan A: no cash reserve
Sarah takes her full £50,000 withdrawal from the investment portfolio.
She sells assets after the market decline.
If weak markets continue, more investments must be sold at depressed prices.
Plan B: cash reserve
Sarah uses £50,000 from cash for the next year.
The investment portfolio remains invested.
She also reduces discretionary travel spending by £5,000.
Markets recover over the following two years.
The cash reserve can then gradually be replenished.
Plan B does not guarantee a better outcome.
But it gives Sarah more control over the timing of withdrawals.
That can be valuable.
Another example: early retirement at 55
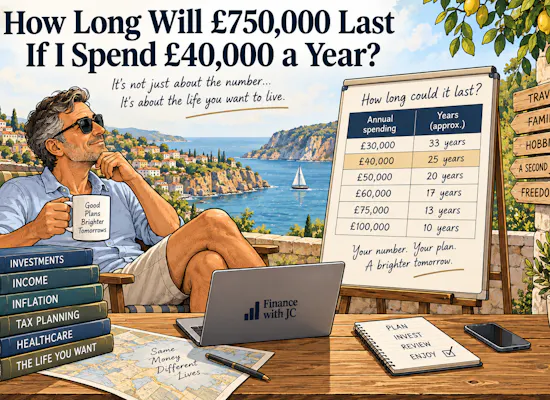
James retires at 55 with £750,000.
He needs £40,000 a year.
That is an initial withdrawal rate of around 5.33%.
If markets immediately fall 20%, the portfolio drops to approximately £600,000.
A £40,000 withdrawal is now around 6.67% of the reduced portfolio.
That is a very different position.
For someone retiring early, sequence risk can therefore be particularly important.
This is one reason How Long Will £750,000 Last If I Spend £40,000 a Year? needs to be answered using stress testing rather than simple division.
Another example: State Pension starts soon
David retires at 65.
He has:
- £700,000 investments
- £40,000 spending
- State Pension beginning at 67
- £10,000 defined benefit pension beginning at 67
Markets fall during his first retirement year.
David only needs to fund the full £40,000 for two years.
After guaranteed income begins, his portfolio withdrawal falls materially.
That makes the sequence-risk problem less severe than it would be for someone retiring at 55 with no other income.
What about property?
If you own rental property, that income may help reduce portfolio withdrawals during weak markets.
But use the net number.
Deduct:
- mortgage costs
- agent fees
- maintenance
- tax
- voids
- insurance
Property can also create liquidity problems.
You cannot easily sell 5% of a rental property to fund one year's spending.
If you are deciding how property fits into retirement, see Should I Sell My UK Rental Property Before I Retire?
What about expats?
Sequence risk applies to everyone.
But expats can have additional complexity.
You may have:
- pension assets in GBP
- investments in USD
- spending in EUR
- cash in AED
- future retirement in another country
If markets fall at the same time as currencies move against you, the impact on spending can be larger.
That is why a cross-border retirement plan needs to look at:
- investment risk
- currency
- tax
- future residence
- pension withdrawals
- cash reserves
For British expats in the UAE, retirement planning for British expats in the UAE specifically connects these issues.
Self-diagnostic: can your retirement plan survive a market fall?
Score one point for each “yes”.
- I know how much essential spending I need each year.
- I know how much spending is discretionary.
- I have an appropriate cash reserve.
- I know where my first three years of withdrawals would come from.
- I have diversified investments.
- I understand my equity exposure.
- I know when State Pension or other guaranteed income begins.
- I have stress tested a 20% to 30% market fall.
- I know which spending I would reduce temporarily.
- I have a rebalancing process.
- I know what I would do instead of panic selling.
- My plan still works if markets are weak for several years.
Green: 9 to 12
Your retirement plan appears to have a reasonable level of resilience.
Amber: 5 to 8
There are some strengths, but the early retirement years need more stress testing.
Red: 0 to 4
The plan may rely too heavily on markets behaving well.
Common mistakes
Assuming average returns arrive smoothly
Problem
The plan assumes the portfolio makes 5% or 6% every year.
Why it matters
Markets do not work that way.
What to do
Stress test different sequences of returns.
Holding no cash reserve
Problem
Every withdrawal must come from investments.
Why it matters
You may be forced to sell after a market decline.
What to do
Keep an appropriate short-term reserve.
Holding too much cash
Problem
Fear of volatility pushes everything into cash.
Why it matters
Inflation and longevity may become bigger risks.
What to do
Keep enough long-term growth exposure.
Refusing to adjust spending
Problem
Withdrawals remain unchanged regardless of markets.
Why it matters
Flexible spending can materially improve resilience.
What to do
Separate essential and discretionary expenditure.
Panic selling
Problem
Growth assets are sold after a major decline.
Why it matters
Losses become permanent and the recovery may be missed.
What to do
Follow a pre-agreed withdrawal and rebalancing plan.
Ignoring the first retirement years
Problem
The same investment strategy is used before and after retirement without review.
Why it matters
The portfolio's job changes once withdrawals begin.
What to do
Review the transition into retirement in advance.
What to review before you retire
Spending
Know the difference between essential and discretionary spending.
Cash
Decide how much near-term expenditure should sit outside volatile markets.
Asset allocation
Make sure the portfolio matches your retirement timeline and withdrawal needs.
Guaranteed income
Map State Pension, defined benefit pensions and other reliable income.
Withdrawal strategy
Know which accounts and investments will fund spending.
Rebalancing
Have a process for restoring the portfolio after markets move.
Tax
Consider the tax impact of drawing from different accounts.
Currency
Expats should make sure near-term spending is not unnecessarily exposed to foreign-exchange movements.
What happens next
Step 1: model a bad first five years
Do not only model average returns.
Step 2: calculate essential spending
Know the minimum amount the portfolio genuinely has to provide.
Step 3: build a short-term reserve
Decide how much spending should be insulated from market volatility.
Step 4: identify future guaranteed income
Map when State Pension and other income starts.
Step 5: create spending guardrails
Decide what could be reduced if markets fall.
Step 6: review the investment structure
Make sure the portfolio still has enough long-term growth.
Step 7: write down the plan
Know in advance what you will do when markets fall.
That way, the decision is made when you are calm.
Not when headlines are frightening.
You may also like
Conclusion
A market fall just after retirement can be uncomfortable.
It can also be financially important.
But it does not automatically ruin the plan.
The real danger is a plan that depends on markets behaving well from day one.
A stronger retirement plan has enough flexibility to deal with:
- falling markets
- temporary spending reductions
- cash withdrawals
- later guaranteed income
- rebalancing
- inflation
- currency
- tax
The aim is not to predict the next market crash.
It is to build a retirement plan that can survive one.
The key question is not:
What happens if markets fall just after I retire?
It is:
Can I continue funding my life without being forced to sell investments at the worst possible time?
If you are approaching retirement and want to know whether your plan can withstand a significant market fall, book an introductory call with Josh Clancey.
FAQ
What is sequence-of-returns risk?
It is the risk that poor investment returns early in retirement, combined with withdrawals, permanently weaken your portfolio.
Why are market falls worse at the start of retirement?
Because you may be withdrawing at the same time the portfolio is falling, meaning assets are sold before they have a chance to recover.
Should I stop withdrawals if markets fall?
Not necessarily. Essential spending still needs to be funded. But reducing discretionary withdrawals can improve resilience.
Should I keep several years of spending in cash?
Possibly. The right amount depends on your spending, guaranteed income and investment strategy. Too little may force selling during downturns, while too much may reduce long-term growth.
Should retirees still own equities?
Often, yes. A long retirement may require growth to help offset inflation and longevity risk. The appropriate allocation depends on your circumstances.
Is a 20% market fall enough to ruin retirement?
Not necessarily. The effect depends on withdrawal rate, asset allocation, cash reserves, future income and spending flexibility.
Does State Pension reduce sequence risk?
It can. Once State Pension or other guaranteed income begins, the amount that needs to be withdrawn from investments may fall.
How can I test whether my plan is safe?
Stress test different market scenarios, including significant losses during the first several years of retirement.
Does sequence risk matter for expats?
Yes. Expats may also need to manage currency, tax residence and pensions in different countries.