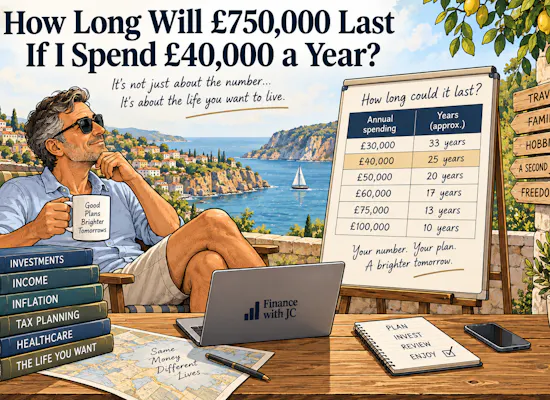
These are illustrations, not recommended withdrawal rates.
They deliberately ignore things such as State Pension, tax, investment returns, inflation and changing expenditure.
But they show something important.
Your retirement number is driven heavily by how much income your investments actually need to provide.
Someone wanting £60,000 entirely from investments needs a very different portfolio from someone who spends £40,000 but will later receive £15,000 from State Pension and defined benefit pensions.
That is why proper retirement income planning for expats starts with cash flow rather than choosing an arbitrary target such as £1 million.
Step 1: work out what retirement actually costs
Do not start with your pension balance.
Start with your life.
What would you actually spend if you stopped working at 60?
It helps to divide spending into three groups.
Essential spending
This may include:
- housing
- groceries
- utilities
- insurance
- healthcare
- transport
- tax
- basic travel
- debt repayments
- family commitments
Lifestyle spending
This might include:
- holidays
- restaurants
- hobbies
- club memberships
- gifts
- entertainment
- upgraded travel
- second homes
One-off spending
This is where many retirement plans fall short.
You may also need money for:
- replacing cars
- home renovation
- helping children
- weddings
- relocation
- major holidays
- medical treatment
- property repairs
- long-term care
- emergency family support
If you think retirement costs £40,000 a year but regularly spend another £15,000 on large one-off items, your real retirement budget is not £40,000.
Step 2: decide where you will live
For an expat, this can change the answer dramatically.
Retiring in Dubai is financially different from retiring in London.
Portugal is different from the UAE.
South Africa is different from the UK.
Your retirement location affects:
- housing
- healthcare
- taxation
- currency
- transport
- insurance
- travel
- family support
- estate planning
If you are a British expat currently based in the UAE, Finance with JC's retirement planning for British expats in the UAE page looks at precisely this issue.
You may not know where you will retire yet.
That is fine.
Model more than one scenario.
For example:
Scenario A: stay in the UAE.
Scenario B: return to the UK.
Scenario C: retire elsewhere in Europe.
You do not need to predict the future perfectly.
You need a plan flexible enough to survive several plausible versions of it.
Step 3: calculate your guaranteed future income
Your investments may not need to fund everything.
List income that may arrive later.
This could include:
- UK State Pension
- defined benefit pensions
- spouse pensions
- Social Security
- overseas state pensions
- annuity income
- rental income
This matters enormously.
Suppose you want £50,000 a year.
From age 67, you expect:
- £12,500 State Pension
- £10,000 defined benefit pension
Your investments then only need to provide about:
£27,500 a year
rather than £50,000.
That produces a very different retirement number.
For 2026/27, the full new UK State Pension is £241.30 per week, although your actual entitlement depends on your National Insurance record.
At that rate, a full year is approximately £12,548.
That is a meaningful contribution to retirement spending.
For a couple who both eventually receive substantial State Pension entitlement, the effect can be larger again.
Step 4: plan the age 60 to State Pension bridge
This is one of the most important parts of retiring at 60.
A 60-year-old in 2026 will generally have a State Pension age of 67 under the current legislated timetable.
So you may need roughly seven years of higher withdrawals before State Pension begins.
Consider someone who needs £50,000 a year.
From age 67 they expect £20,000 of combined guaranteed pension income.
The plan may look like this:
Age 60 to 66
Required from investments:
£50,000 a year
Age 67 onwards
Required from investments:
£30,000 a year
This is very different from assuming the portfolio needs to fund £50,000 every year forever.
Your retirement number should reflect the actual income timeline.
Step 5: understand what a withdrawal rate does and does not tell you
You will often see retirement planning reduced to a withdrawal percentage.
For example:
4% of £1 million = £40,000.
That is useful.
But it is not a guarantee.
A sustainable withdrawal depends on:
- retirement age
- time horizon
- investment strategy
- market returns
- inflation
- charges
- tax
- spending flexibility
- guaranteed income
- legacy goals
Someone retiring at 60 may reasonably expect the assets to support several decades of withdrawals.
The plan therefore needs to survive more than the average investment return.
It needs to survive difficult periods.
Step 6: allow for inflation
Suppose you need £50,000 today.
If inflation averages 2.5%, maintaining the same purchasing power would require approximately:
- £56,600 after five years
- £64,000 after ten years
- £72,400 after fifteen years
- £81,900 after twenty years
You do not need to predict inflation precisely.
But pretending it does not exist is worse.
Retirement may last three decades.
Over that timeframe, inflation matters enormously.
This is why simply saying:
“I need £50,000 × 30 years = £1.5 million”
does not produce a reliable answer either.
Your assets may grow.
Spending rises.
Pensions start.
Tax changes.
Your lifestyle changes.
The calculation needs to model all of those together.
Step 7: account for sequence-of-returns risk
Suppose two people retire at 60 with identical portfolios.
Both achieve the same average investment return over 25 years.
One enjoys excellent returns during the first five years.
The other experiences a major market decline immediately after retiring.
Their eventual outcomes can be very different.
Why?
Because the second retiree is withdrawing money while markets are down.
That means assets are sold at depressed prices and are no longer there to participate fully in the recovery.
This is sequence-of-returns risk.
It is one of the most important risks immediately before and after retirement.
That is why retirement planning may involve:
- cash reserves
- diversification
- withdrawal flexibility
- lower-risk assets for near-term spending
- regular portfolio rebalancing
- reducing discretionary spending during poor markets
A portfolio built solely for accumulation may need to change as retirement approaches. Finance with JC covers this within its existing retirement planning for expats framework.
Step 8: decide how much cash you need
Retiring does not mean putting everything into cash.
But entering retirement without enough accessible cash can leave you vulnerable.
You may want cash for:
- routine spending
- emergency expenses
- planned large purchases
- market downturns
- property costs
- healthcare
- relocation
The aim is not to eliminate investment risk.
It is to avoid being forced to sell long-term investments at the worst possible moment.
Step 9: include tax
The amount you need to spend is not necessarily the amount you need to withdraw.
Suppose you need £50,000 in your bank account.
If all £50,000 comes from taxable pension income, you may need to withdraw more than £50,000 gross.
If instead income comes from a mixture of:
- pensions
- ISAs
- cash
- investments
- tax-free pension cash
- rental income
the tax result may be different.
For expats, it can become more complicated again.
Tax may depend on:
- UK residence
- overseas residence
- pension type
- double-taxation agreements
- whether you later return to the UK
If you hold UK pensions while abroad, your retirement planning should also consider what happens to your UK pension when you move abroad.
Step 10: understand your pension access
By age 60, most people with UK defined contribution pensions will already be above the normal minimum pension age.
The normal minimum pension age is currently 55 and is scheduled to increase to 57 from 6 April 2028, subject to protections and exceptions.
So access itself is unlikely to be the main issue at age 60.
The more important questions become:
- how much should you take?
- when should you take it?
- should you use drawdown?
- how much tax-free cash should you take?
- how should the remaining pension be invested?
- how does the pension interact with other assets?
The standard lump sum allowance remains £268,275 for 2026/27, subject to individual circumstances and any protections.
But being able to take tax-free cash does not automatically mean you should take the maximum amount at retirement.
The money needs a purpose.
Step 11: include everything you own
Your retirement number should not be confused with your pension number.
You may have:
- pensions
- investment accounts
- cash
- ISAs
- offshore investments
- property
- rental property
- business interests
- end-of-service benefits
- deferred compensation
- spouse assets
Someone with a £600,000 pension and £500,000 of investments may be in a stronger position than someone with a £900,000 pension and no other liquid capital.
The structure matters.
So does flexibility.
Step 12: decide whether your home is part of the plan
Your home has value.
But it does not automatically produce retirement income.
If you own a £1 million home and have £250,000 invested, you do not necessarily have £1.25 million available to fund retirement.
Unless you intend to:
- sell
- downsize
- borrow against it
- rent part of it
- relocate somewhere cheaper
the property may be better viewed as a lifestyle asset.
On the other hand, planned downsizing at 70 could release significant capital later.
That should be included in the plan if it is realistic.
Step 13: consider whether rental property stays
You may also own investment property.
Do not simply count the market value.
Ask what it contributes.
Calculate rental income after:
- mortgage
- agents
- maintenance
- tax
- insurance
- voids
- service charges
Then decide whether the property still deserves a place in retirement.
If you are already thinking about this, see Should I Sell My UK Rental Property Before I Retire?
Step 14: decide whether you want to spend the capital
This changes the answer considerably.
Some people want:
“Enough so that I never touch the original capital.”
Others want:
“Enough so that I can enjoy retirement even if the portfolio gradually reduces.”
Others want:
“Enough to leave £1 million to my children.”
Those are three different retirement numbers.
There is nothing inherently wrong with spending capital in retirement.
That is partly what it was accumulated for.
But your estate objective needs to be explicit.
Worked example 1: £40,000 spending and a paid-off home
James retires at 60.
He wants £40,000 a year.
He owns his home outright.
At 67, he expects approximately £12,500 of State Pension.
He has no defined benefit pension.
From age 60 to 66, investments provide approximately:
£40,000 a year
From age 67, the portfolio requirement falls to roughly:
£27,500 a year
A £1 million portfolio therefore has a very different job from one required to provide the whole £40,000 indefinitely.
James may need materially less capital than a simplistic £40,000 × 30 calculation suggests.
Worked example 2: £60,000 lifestyle
Sarah retires at 60.
She wants £60,000 a year after tax.
She rents rather than owns her home.
She has limited guaranteed pension income later.
Her retirement number needs to be materially higher.
A £1 million portfolio requiring £60,000 from the first year starts at a 6% gross withdrawal before even allowing for tax.
That makes the plan much more sensitive to:
- market falls
- inflation
- longevity
- housing costs
She may need more capital, lower spending, additional income or a later retirement date.
Worked example 3: British expat leaving Dubai
Mark is 60 and lives in Dubai.
He has:
- £650,000 of UK pensions
- £450,000 of international investments
- £100,000 cash
- UK State Pension entitlement
- no debt
Total investable assets:
£1.2 million
He wants £50,000 a year but is unsure whether he will retire in the UAE, UK or Portugal.
His retirement number cannot be tested properly until those scenarios include:
- tax
- currency
- housing
- healthcare
- pension withdrawals
- future State Pension
- estate planning
This is why retirement planning for British expats in the UAE needs to be cross-border rather than simply asking how large the pension is.
Worked example 4: £750,000 and £40,000 spending
David retires at 60 with £750,000.
He wants £40,000 a year.
That is an initial withdrawal of around 5.33%.
But at 67 he expects State Pension and another small pension totalling £17,000 a year.
His required portfolio withdrawal then falls to £23,000.
The plan is considerably stronger than assuming £40,000 must come from the portfolio forever.
The timing of income matters as much as the headline asset figure.
Worked example 5: £1.5 million but high spending
Emma has £1.5 million at 60.
That sounds comfortably wealthy.
But she wants:
- £90,000 annual spending
- significant travel
- ongoing rent
- regular family support
- a substantial inheritance for her children
Her starting withdrawal requirement is high.
The issue is not whether £1.5 million is a lot of money.
It is whether £1.5 million can meet her particular objectives.
That distinction is crucial.
A simple retirement-number framework
A useful way to think about the calculation is:
1. What do I want to spend?
For example:
£50,000 a year.
2. What guaranteed income arrives later?
For example:
£15,000 State Pension and DB income.
3. What does the portfolio need to provide?
Before guaranteed income:
£50,000.
Afterwards:
£35,000.
4. How long does each phase last?
Perhaps seven years of higher withdrawals followed by lower withdrawals.
5. What other assets exist?
Cash, investments, property and spouse assets.
6. What could go wrong?
Poor returns, inflation, longevity, health costs or higher spending.
7. What margin of safety do I want?
This is where the retirement number becomes personal.
Self-diagnostic: are you ready to retire at 60?
Score one point for each “yes”.
- I know my annual essential spending.
- I know my annual discretionary spending.
- I have allowed for large one-off costs.
- I know where I expect to retire.
- I know my State Pension forecast.
- I know when every pension starts.
- I know how much income my investments need to provide.
- I understand how tax affects withdrawals.
- I have allowed for inflation.
- I have stress tested poor investment returns.
- I have an appropriate cash reserve.
- I know how much I want to leave behind.
Green: 9 to 12
You have most of the information required to test the retirement plan properly.
Amber: 5 to 8
Retirement may be achievable, but important assumptions are missing.
Red: 0 to 4
Do not base retirement on your pension balance alone. The cash-flow plan needs more work.
If this feels familiar, Finance with JC has a specific page for people who are approaching retirement and not sure whether they have enough.
Common mistakes
Picking an arbitrary target
Problem
Someone decides they need £1 million because it sounds like the right retirement number.
Why it matters
£1 million means nothing without the spending requirement.
What to do
Calculate the lifestyle first.
Forgetting State Pension
Problem
The portfolio is assumed to provide the full retirement income forever.
Why it matters
State Pension or other guaranteed income may materially reduce withdrawals later.
What to do
Map income by age.
Ignoring inflation
Problem
£50,000 spending is assumed to remain £50,000 for life.
Why it matters
Purchasing power gradually falls.
What to do
Model spending in real terms.
Using one withdrawal percentage blindly
Problem
A fixed rule is applied regardless of age or circumstances.
Why it matters
Retirement length, guaranteed income and spending flexibility differ.
What to do
Model the actual cash flows.
Ignoring market falls
Problem
The plan assumes smooth investment returns.
Why it matters
Poor returns immediately after retirement can materially reduce sustainability.
What to do
Stress test adverse sequences.
Counting the house as spendable wealth
Problem
Total net worth is confused with investable capital.
Why it matters
A home cannot fund spending unless you intend to release its value.
What to do
Separate lifestyle and investment assets.
Ignoring tax
Problem
The retirement target is based on gross withdrawals.
Why it matters
What matters is what reaches your bank account.
What to do
Model net spendable income.
What to review before retiring at 60
Spending
Work out what you actually spend rather than what you think you spend.
Pensions
Review State Pension, defined benefit pensions, defined contribution pensions, SIPPs and overseas retirement accounts.
For British expats in Dubai, UK pension advice in Dubai can form part of this review.
Investments
Review portfolio risk, diversification, charges, liquidity, currencies and suitability for withdrawals.
Tax
Model where the income comes from and where you will be tax resident.
Property
Decide whether property is for income, future use, downsizing or eventual sale.
Cash
Set aside enough liquidity so short-term expenditure does not depend on selling investments at the wrong time.
Estate planning
Decide how much capital you want or need to leave behind.
What happens next
Step 1: calculate your current spending
Use actual bank and card statements.
Step 2: design your retirement lifestyle
Remove work-related costs and add the things you expect to do more of.
Step 3: map every future income source
Put State Pension, DB pensions, rental income and other income onto a timeline.
Step 4: calculate the gap
Work out how much must come from pensions and investments.
Step 5: model the plan
Include tax, inflation, investment returns and changing spending.
Step 6: stress test it
Ask what happens after a bad five years, higher inflation or an expensive unexpected event.
Step 7: decide whether age 60 works
You may find that you can retire now.
You may need another two years.
You may be able to semi-retire immediately.
Or you may discover that you already have more than enough.
That is what the calculation is supposed to tell you.
You may also like
Conclusion
There is no universal amount you need to retire at 60.
The answer is not automatically:
£500,000.
It is not automatically:
£1 million.
And it is not automatically:
25 times your annual spending.
Your retirement number depends on the life you actually want to fund.
You need to know:
- what you will spend
- where you will live
- when guaranteed pensions start
- what tax may apply
- how long the capital needs to last
- how investments are structured
- how much flexibility you have
- what you want to leave behind
A £750,000 portfolio can be enough for one household and nowhere near enough for another.
A £1.5 million portfolio can provide huge security for one person and still be stretched by another person's lifestyle.
The balance alone does not answer the question.
The cash flow does.
The key question is not:
How much money do I need to retire at 60?
It is:
How much do I need to fund the retirement I actually want, with enough resilience to deal with whatever happens along the way?
If you are approaching retirement and want to know what your number is, book an introductory call with Josh Clancey.
FAQ
How much money should I have to retire at 60?
There is no universal target. Work backwards from spending, other pensions, tax, inflation and how long retirement may last.
Is £500,000 enough to retire at 60?
It may be for someone with moderate spending, a paid-off home and significant State Pension or other pension income later. It may not be enough for a higher-spending household.
Is £1 million enough to retire at 60?
Potentially. £40,000 from £1 million represents a 4% initial withdrawal, but whether that is sustainable depends on investment returns, inflation, tax, other income and retirement length.
What income does £750,000 provide?
A £30,000 annual withdrawal is 4% of £750,000. £40,000 is approximately 5.33%. These are starting withdrawal rates rather than guaranteed sustainable income levels.
When will I get State Pension if I retire at 60?
It depends on your date of birth. Under the current timetable, State Pension age is increasing from 66 to 67 between 2026 and 2028, and those born from 6 March 1961 to 5 April 1977 currently have a State Pension age of 67.
How much is the full UK State Pension in 2026/27?
The full new State Pension rate for 2026/27 is £241.30 per week, although your actual entitlement depends on your National Insurance record.
Should I include my house in my retirement number?
Only if you genuinely plan to release capital from it through downsizing, selling or another strategy. Otherwise, it is normally more useful to separate your home from investable retirement assets.
Does retiring abroad change how much I need?
Yes. Cost of living, healthcare, tax, housing, currency and future residence can materially alter the calculation.
What is the best way to know if I can retire at 60?
Build a cash-flow model incorporating your actual spending, pensions, investments, tax, inflation, property, State Pension, investment returns and adverse scenarios.